Retirement Savings Need A Plan For Income Taxes And Family Wealth
By Mark Hui | Vancouver City News | November 20,2026
Having RRSPs, TFSAs and investments is a strong start. A retirement plan connects those accounts with income protection, government benefits, spending needs, taxes and family legacy.
Just because you have an RRSP, a TFSA or investments does not necessarily mean you have a financial plan.
Since entering financial services in 2005, I’ve met Canadian families who have worked hard to save. They have investment accounts, workplace pensions and money set aside for the future.
That is worth celebrating. But the next question is: How do all those pieces work together?
Consider a client situation involving a couple, both age 65, preparing to retire and exploring withdrawals through RRIFs.
The wife has:
The husband has:
His pension’s indexing and relationship with CPP also need clarification through the pension documents. Inflation indexing and CPP integration are different features.
Together, they have approximately $1.5 million in the listed investment accounts, plus the husband’s pension.
The good news is that they have accumulated substantial savings. The challenge is deciding how to turn those assets into reliable income while managing taxes and preserving flexibility.
Which accounts should provide income first? How much should remain invested? What happens financially when one spouse dies?
An account statement cannot answer those questions on its own.
For Canadians approaching retirement, CPP presents an important choice: start as early as 60, begin at 65 or wait until 70 for a larger monthly payment?
For this couple, already age 65, the decision centres on their current benefit status and whether delaying future payments makes sense.
Questions worth examining include:
CPP estimates should come from each person’s contribution record, rather than an assumption that everyone receives the maximum. Source: Government Of Canada
OAS requires its own review:
OAS eligibility and payment amounts depend on personal circumstances, including residence history and income. Recovery-tax thresholds also depend on the applicable year. Sources: OAS Benefit Amounts and OAS Recovery Tax
The best starting age may differ between spouses. A larger future payment needs to be weighed against payments forgone while waiting and savings used to bridge the gap.
Strong investment growth is welcome, but larger registered balances can lead to larger taxable withdrawals later.
For this couple, a projection using returns above 8% would warrant examining whether their withdrawal choices could expose either spouse to OAS recovery tax around age 70.
That is a scenario to test, not a confirmed outcome. Neither an 8% return nor reaching age 70 automatically triggers a clawback.
OAS recovery tax depends on each person’s income and the applicable threshold. Growth retained inside an RRSP does not itself create that year’s taxable withdrawal income.
Future returns, withdrawals, pension income, benefit timing and eligible pension splitting all influence the result. Source: CRA — Pension Income Splitting
RRIF minimum payments begin in the year after the account is established. RRSPs must generally be settled by the end of the year the owner turns 71, through withdrawal, conversion to a RRIF or an eligible annuity. Sources: RRIF Payments and RRSP Options At Age 71
The objective is to compare lifetime outcomes, rather than focus only on avoiding one tax.
I find it useful to consider three connected phases.
During our working years, we build savings, manage debt and invest toward future goals. We also need to consider what happens if the income supporting those goals stops.
Life insurance can help support a family financially after a death. Disability insurance can replace part of lost income when a covered disability prevents someone from working. Critical illness insurance can provide a lump sum following a covered diagnosis, subject to policy conditions.
The appropriate protection depends on family responsibilities, workplace benefits, existing savings and policy terms. The purpose is to help prevent an unexpected event from forcing the family to abandon its long-term plans.
Retirement is when accumulated resources begin supporting everyday life. A plan needs to consider a potentially long retirement and the risk of outliving available savings.
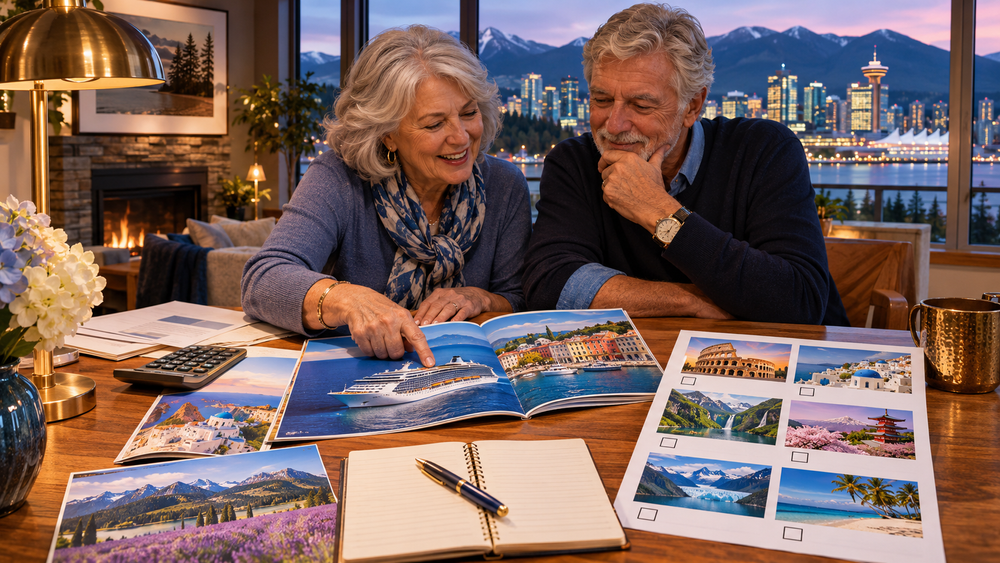
Earlier years may involve more travel, hobbies and activities while health and energy allow.
Later years may bring a slower pace, additional care or retirement-home costs. These stages vary by person, and spending does not necessarily decline as activity slows.
A useful plan allows adjustments as needs change.
Succession concerns what happens to the remaining wealth and how it reaches the next generation.
That includes managing potential taxes, reviewing beneficiaries, protecting the surviving spouse and ensuring estate documents reflect family intentions.
Decisions made during accumulation and retirement can affect what eventually remains for loved ones.
It is tempting to say everything becomes a taxable deemed disposition at death. The actual rules differ by asset.
Capital property may be deemed sold at fair market value. RRSP and RRIF balances generally follow income-inclusion rules, with qualifying transfers potentially deferring tax.
A TFSA’s value at death generally passes tax-free, although subsequent earnings may be taxable. A qualifying spouse named successor holder can preserve its tax-exempt status. Sources: Reporting After Death, RRIF Treatment and TFSA Treatment
Beneficiary designations, spousal transfers, wills and available cash to pay taxes all deserve attention.
A financial plan brings savings, protection, debt, government benefits, taxes and retirement income into one direction.
For this couple, the next step is comparing scenarios using verified pension details, personal benefit estimates, actual spending needs and realistic investment assumptions—including lower returns.
There may be more questions than answers at the beginning. Those questions reveal the decisions that deserve attention.
Like travelling, planning requires a destination and adjustments along the way. Your route can change as circumstances do.
Money is a tool for creating choices. A plan helps connect it with the life—and family legacy—you want.
By Mark Hui | Financial Services Professional | Vancouver City News Contributor
Since 2005, I’ve helped Canadians understand how financial decisions connect with their family goals. My approach starts with understanding what people want to protect, enjoy and eventually pass on.
Mark Hui is a BC-based financial services professional working with individuals, families and business owners. He focuses on clear education and practical conversations about changing needs.
Connect: LinkedIn | Instagram | Facebook
Mark Hui
WBN News – Real-Time Intelligence For Business
Contact: mhui056vvc@wfgmail.ca
Tags: #Retirement Planning #Financial Education #Income Protection #Estate Planning #Financial Literacy #Mark Hui #Vancouver City News
IMAGE PROMPT
Sources